Financial advice that starts with a plan.
We help you do more with what you’ve earned.
Last updated: January 2026
Credit cards designed for those who spend significant amounts of money become a gateway to a world of luxury. If your income is high and this type of spending works for you, it’s something to consider as part of your wealth management strategy.
Yet, with so many credit card offerings specifically for high-income earners, which cards deliver the most advantageous benefits for you?
- Centurion (Black Card) from American Express →
- American Express Platinum →
- JP Morgan Reserve →
- Chase Sapphire Reserve →
Overview Chart
| Card | Annual Fees | Pros | Cons |
|---|---|---|---|
| Centurion (AMEX Black) | ~$10,000 initiation + $5,000 annual | Ultra-elite access, concierge, prestige | Extremely high cost, weak point earnings, narrow use case |
| Amex Platinum | $895 annual | Balanced travel + lifestyle credits, strong perks | Must activate/use multiple credits or lose value |
| JP Morgan Reserve | Unchanged/Private | Deep banking integration, bespoke privileges | Only for ultra-wealthy clients; not standalone |
| Chase Sapphire Reserve | $795 annual | High multipliers via Chase Travel, flexible redemptions | Must conform to their portals/booking constraints |
Navigating the Prestige Credit Card Landscape
For high-net-worth people, the choice of a credit card is less about the transaction and more about the value-add. Note: If you’re a high earner looking for help managing the bigger financial picture, learn more about how we work with clients like you.
Prestige cards, such as the Centurion Card from American Express, cater to a lifestyle, offering transactional benefits and exclusive access to events and luxury travel perks. The Chase Sapphire Reserve appeals to frequent travelers, offering substantial travel credits and streamlined security processes.
Yet, these cards involve a cost-benefit analysis. The JP Morgan Reserve, for instance, rewards investment-heavy spending but, like its counterparts, demands a significant annual fee. To be invited to apply for the card, you must maintain an investment portfolio of $10M+ managed by the J.P. Morgan private bank.
The right elite credit card for affluent clients matches your financial strategy and lifestyle, going beyond surface-level benefits to offer genuine, measurable value.
A quick note on the new Citi Strata Elite card. This is an attempt for Citi to break into the premium credit card market. They’ve stumbled out of the gate, with reports that cardholders have been locked out of their accounts. Until there is a drastic change on Citi’s part, we have removed them from our list.
1. Centurion from American Express
Often shrouded in myth, the Centurion AMEX, also known as the Black Card, symbolizes ultra-prestige. Yet beyond its lore lies a suite of services befitting its status, like exclusive travel upgrades and by-invitation-only events. Is its cachet justified? It may well be for those who capitalize on its full spectrum of services.
What’s New
- The most broadly cited current rumor is that it commands a $10,000 initiation fee plus a $5,000 annual fee.
- Additional (authorized) cardholders reportedly incur the full $5,000 annual fee each.
- The point-earning structure remains weak: cardmembers typically earn 1 Membership Rewards point per dollar spent, with little to no bonus multipliers.
Pros
- Exclusivity & Status: The invitation-only nature ensures the card is rare and consequential.
- Premium travel upgrades & perks: Cardholders often receive elite status, upgrades, airport services, etc.
- Concierge & lifestyle service: Concierge can handle high-complexity requests, saving time and reducing friction for ultra-high-net-worth users. This alone, for the right crowd, can be worth the weak point-earning structure.
Cons
- Astronomical cost: The combination of initiation and annual fees ($15,000 first year, if rumors hold) means you need extremely high usage of perks to break even.
- Poor returns on spend: With 1× point on everything, you lose many of the earnings multipliers found in slightly lower-tier ultra-premium cards.
- Narrow applicability: For all but the ultra elite, many of its advantages will go unused or redundant with other cards you hold.
Bottom Line
If you already live at a level where a dedicated concierge, ultra-elite status, and token access are materially useful and you can consume/monetize those services, the Centurion may be justified. Otherwise, the steep cost is hard to justify.
Do more with what you’ve earned.
You’ve worked hard to get here. We build financial plans around your actual life so you can make the most of it.
2. American Express Platinum
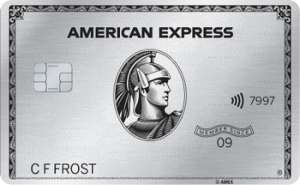
This card strikes a balance between luxury and practical reward structures. With substantial travel credits and a generous points system, it’s engineered for those who seek value in every transaction. Its merit lies in its ability to convert fees into discernible lifestyle enhancements.
What’s New
- Annual fee: $895 (up from $695).
- Expanded credits & perks:
• $600 hotel credit (via prepaid bookings through Amex’s Fine Hotels + Resorts / The Hotel Collection)
• $400 dining / Resy credit (up from prior dining perks)
• $300 credit for Lululemon purchases
• New digital entertainment/streaming credits, expanded wellness perks (e.g., Oura Ring, etc.)
• Many of the existing benefits (airport lounge access, elite hotel status, airline incidental credits, etc.) remain but may require enrollment or activation.
Pros
- Solid point structure: It keeps its strong multipliers for flights/hotels booked via Amex or directly.
- Versatile credits: The expanded hotel, dining, wellness, and entertainment credits help amortize the higher fee.
- Lifestyle + travel blend: Not just travel. The perks now cover lifestyle and wellness more strongly.
Cons
- High bar for full utilization: To unlock full ROI, you must consistently use a wide range of credits and perks.
- Complexity: Many perks require activation, enrollment, or spending through specific portals. If you miss deadlines, you lose value.
- Still travel-skewed: If you don’t travel much, many benefits may go underused.
Bottom Line
Amex repositioned Platinum to lean further into lifestyle and wellness, not just travel. The $895 fee is offset only if you take advantage of the expanded credits (hotel, dining, apparel, streaming). Frequent travelers and lifestyle consumers who can spread usage across travel, dining, and wellness to fully extract value from the credits.
3. JP Morgan Reserve
A bastion of exclusivity, available to select bank clientele, promises a bespoke financial experience. Its rewards are tailored to integrate with significant investment portfolios, challenging the cardholder to leverage its potential fully.
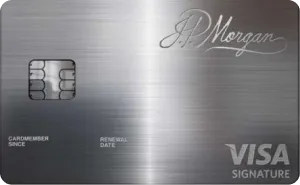
Otherwise known as the Palladium Card, it is the card for the 1% of the 1%. This is an invite-only card, with a reported minimum of $10MM under management at JP Morgan.
It is important to note that the JP Morgan Card is also quite heavy, weighing 27 grams, as it is made with brass and palladium. It weighs almost twice as much as most other luxury credit cards.
What’s the heaviest credit card by weight?

If you are looking to impress your friends at dinner by throwing your card onto the table, the JP Morgan Reserve is the heaviest credit card.
Pros:
Select Clientele: Available exclusively to JP Morgan’s private clients with over $10M in managed investments, this card not only offers an air of exclusivity but also ensures privacy, as ownership details are not reported to credit bureaus, thus maintaining the cardholder’s financial discretion.
Rewards Synced with Investments: Its rewards system complements substantial investment portfolios, potentially enhancing overall financial strategy.
Holistic Financial Tool: The card serves as a hub for managing spending and investments, streamlining financial oversight.
Cons:
Niche Audience: Its benefits cater specifically to those with significant investments and banking relationships with JPMorgan.
Optimization Required: To fully benefit, cardholders must actively engage with the card’s features and integrate them into their broader financial activities.
The JP Morgan Reserve card best suits investors actively utilizing its investment-synced rewards, merging spending power with financial growth strategies.
Bottom Line
Ideal for those already deeply invested in the JP Morgan private banking ecosystem who can use the card not just for spending, but as a functional lever in their wealth strategy.
Do more with what you’ve earned.
You’ve worked hard to get here. We build financial plans around your actual life so you can make the most of it.
4. Chase Sapphire Reserve
With a robust rewards program and a suite of travel benefits, it stands as a testament to functionality. It’s a card that not only spends but also adds value with every use, making it a contender for those who desire utility as much as luxury.
What’s New
- Annual Fee Increase: $795 (up from $550)
- Authorized user fee increase: From $75 to $195.
- Rewards overhaul:
• 8× points on travel booked through Chase Travel (including flights, hotels, cruises) across the board.
• 4× points when booking flights and hotels directly, rather than via the Chase Travel portal.
• Travel booked via non-Chase channels drops to 1×. - Redemption/points value update: The old 1.5× multiplier for travel redemptions via Chase’s travel portal is being replaced with a more selective “Points Boost” feature, where only certain bookings are eligible for enhanced value.
- New / enhanced credits & benefits:
• Up to $500 in hotel credit under “The Edit” program for prepaid bookings.
• The existing $300 general travel credit remains.
• Dining, entertainment, subscription, and ride credits are being added or expanded to sweeten the value.
Pros:
- Strong returns for travel spend: If you book smartly (via Chase Travel or direct), you can receive fairly significant benefits.
- New hotel credit flexibility: The $500 hotel credit is a welcome boost.
- Versatile redemption: The Points Boost model enables selective multipliers for high-value bookings.
Cons:
- Higher bar to break even: With $795 in fees, you’ll need to use credits and bookings to extract value consistently.
- Restrictions on which bookings qualify for extra multipliers: If you don’t use the “right” channels, your rewards drop sharply.
- Transition complexity: Existing cardholders must navigate the switch to the new regime (especially around redemption rules).
Bottom Line
Chase is pushing the Sapphire Reserve further into the ultra-premium space, increasing both cost and upside potential. It is more “all in” on travel bookings via its own platform. Heavy travelers who won’t shy from using the Chase Travel portal, and who can book high spend on flights/hotels year-round. If your travels are infrequent or you use niche airlines/hotels, the constraints may reduce their appeal.
The Unofficial Fifth Contender: Marriott Bonvoy Brilliant Card
While not officially on our list, the Marriott Bonvoy Brilliant card still deserves an honorary mention for those whose travel revolves around Marriott properties. If you don’t have a preferred airline but value consistently elevated hotel experiences, this card is one of the most compelling options.
What’s new / updated:
- Annual fee: $650, but the perks have increased in value.
- Elite status: Cardholders are automatically elevated to Bonvoy Platinum Elite status, unlocking complimentary room upgrades, late checkout, welcome gifts, and enhanced earning on stays.
- Free Night Award: Receive an annual free night award worth up to 85,000 points, which alone can offset most (or all) of the annual fee if redeemed strategically.
- Dining credit: Up to $300 in dining credits per year ($25 monthly statement credit for eligible restaurant purchases) — a notable upgrade from the old $100 credit.
- Rewards structure:
• 6× points on eligible Marriott purchases
• 3× points at U.S. restaurants and on flights booked directly with airlines
• 2× points on all other eligible purchases
For frequent Marriott guests, these changes make the Brilliant card even more compelling. The combination of elite status, a valuable free night certificate, and monthly dining credits can make the annual fee more than pay for itself — even with moderate usage.
Bottom Line
Travelers who consistently stay with Marriott or want their hotel card to feel more like a premium travel card. When paired with a more flexible points-earning card like the Chase Sapphire Reserve or Amex Platinum, it can round out a high-end travel rewards strategy.
Integrating Your Credit Card Into Your Financial Plan
Navigating the world of premium credit cards requires more than an appreciation for their perks. It requires a strategic approach that complements your broader financial objectives. The right mix of cards should not only enhance your lifestyle but also align with how and where you spend, helping you extract meaningful value from every transaction.
Optimizing Card Usage with Professional Guidance
Working with a fiduciary advisor can bring a more sophisticated layer to your financial strategy. Bull Oak’s team can help you evaluate which cards truly add value, maximize rewards, and integrate these benefits into a broader wealth plan, turning everyday spending into a more efficient part of your financial life.
Choosing the right credit card as a high earner isn’t about status. It’s about capitalizing on the wealth you’ve built. Learn how Bull Oak can help you make every dollar work harder.